

Last Updated: October 29, 2026
Quick Summary
To categorize expenses, list your income and bills, pick a starter set of 8-12 categories, assign every transaction to exactly one category, then review and adjust monthly. The setup takes about an hour, and the goal is a system you will keep using rather than a perfect one.
- Start with categories like housing, utilities, groceries, transportation, insurance, healthcare, debt payments, savings, and discretionary spending.
- Exclude transfers between accounts you own, since moving money is not spending.
- Offset refunds against the original category instead of counting them as income.
- Merge categories with fewer than three transactions a month and split any group over about 30% of spending.
- Divide yearly irregular costs by twelve to create a monthly sinking fund category.
Table of Contents
- Why Categorizing Expenses Makes Budgeting Easier
- How to Create Expense Categories in 4 Steps
- Budget Categories With Examples for Beginners
- Fixed and Variable Expenses: What Goes Where
- Building an Irregular Expenses Budget
- Using an Expense Tracking Spreadsheet to Stay Consistent
- Handling Refunds, Transfers, and Shared Purchases
- Set Up Your First Expense Categories With the 1-Hour Budget Setup Guide
- Frequently Asked Questions
Why Categorizing Expenses Makes Budgeting Easier
Categorizing expenses is the practice of sorting every transaction into a named group, like housing, groceries, or transportation, so you can see where your money actually goes. A list of transactions tells you what you spent. Categories tell you why.
Below, we'll show you how to categorize expenses for beginners, with a four-step setup, a starter list, and answers to the messy situations most guides skip.
How to Create Expense Categories in 4 Steps
Creating expense categories takes about an hour: list your income and bills, pick a starter set of 8-12 groups, assign every transaction to one, then review monthly. The goal is not a perfect system but one you will keep using.
Step 1: List Your Monthly Income and Bills
Start with money in and money out. Write down every income source, then every bill with its due date. This gives you the frame your categories will hang on.
If bills feel tangled, our guide to the best way to track monthly bills walks through a simple listing system first.
Step 2: Pick a Starter Set of Categories
Start with: housing, utilities, groceries, transportation, insurance, healthcare, debt payments, savings, and discretionary spending. Add subcategories later once a group gets crowded.
Step 3: Assign Every Transaction to One Category
Every transaction gets exactly one home. No splitting, no double labels. If a purchase fits two categories, pick the one that best describes why you bought it and move on.
The beginner decision tree for ambiguous purchases
When a transaction could fit two categories, run it through these four questions in order. Stop at the first question that gives you a clear answer.
- Is it a transfer between accounts you own? If yes, exclude it entirely. Moving money is not spending. This covers credit card payments, savings transfers, and brokerage contributions.
- Is it a refund or reimbursement? If yes, offset the original category rather than counting it as income. A returned jacket reduces clothing spending; it does not add to earnings.
- What was the primary reason you bought it? Choose the category that describes the need, not the store. Batteries from the grocery store are household supplies, not groceries, if the reason was a dead remote.
- Would a reasonable person put it in the same bucket next month? If yes, commit and write the rule down. If no, it belongs in a catch-all like "discretionary" until a pattern emerges.
Personal versus business: pick one scope before you start
Decide your scope first.
- Personal budgeting scope: categories describe your life (housing, groceries, transportation). The goal is visibility and control.
- Business bookkeeping scope: categories must map to tax-deductible line items (advertising, contract labor, supplies, travel). The goal is accurate records and clean Schedule C reporting.
If you run both, keep two separate category sets and never mix them in one ledger. A business lunch logged as "groceries" distorts both your household budget and your deduction records.
Step 4: Review and Adjust Monthly
Set a short monthly review to check your category totals. Look for categories that blew past expectations and categories you never used.
Then adjust. Merge the empty ones, split the crowded ones. If overspending keeps throwing off your categories, learn how to stop overspending every month with a simple plan.
When to merge or split a category
Category design is maintenance, not a one-time setup. Use these rules:
- Merge two categories when you cannot remember which one a purchase went into, or when one category has fewer than three transactions a month. Two thin categories are harder to read than one clear one.
- Split a category when a single group is more than about 30% of your spending and you cannot tell which part is growing. "Shopping" that includes clothes, gifts, and home goods should become three categories once it dominates your budget.
- Retire a category after two months of zero use. Empty categories add clutter and slow your review.
A useful sanity check: if you cannot explain a category's total to a friend in one sentence, it is either too broad or too narrow.
Budget Categories With Examples for Beginners
A beginner budget category list can cover essentials, goals, and flexible spending. Each category below includes a definition, common subcategories, and a rule of thumb so you can copy it straight into a spreadsheet or app. Treat it as a starter taxonomy and adjust names to match how you actually talk about money.
The starter taxonomy
| Category | What belongs here | Common subcategories | Rule of thumb |
|---|---|---|---|
| Housing | Shelter costs you pay to keep a roof over your head | Rent or mortgage, renters or homeowners insurance, HOA dues, property tax (if paid directly) | |
| Utilities | Recurring home services | Electric, gas, water, sewer, trash, internet, phone | Fixed portion (internet, phone) plus variable portion (electric, water) |
| Groceries | Food and household consumables bought to prepare at home | Supermarket runs, farmers market, household supplies like paper goods and cleaning products | Separate dining out entirely; do not mix restaurants into groceries |
| Transportation | Getting from place to place | Gas, transit passes, rideshare, parking, car maintenance, registration | Track gas and maintenance separately if you drive a lot |
| Insurance | Premiums you pay directly | Auto, health (if self-paid), life, disability | Exclude premiums deducted from a paycheck to avoid double counting |
| Healthcare | Out-of-pocket medical costs | Prescriptions, copays, dental, vision, therapy | Keep separate from insurance premiums |
| Debt payments | Required payments on borrowed money | Credit cards, student loans, car loans, personal loans | Track minimums here; extra payments can go to savings goals |
| Savings | Money you keep on purpose | Emergency fund, sinking funds, retirement contributions outside payroll | Pay yourself like a bill, not like leftovers |
| Discretionary spending | Wants, not needs | Dining out, hobbies, gifts, entertainment, personal care | |
| Subscriptions | Recurring digital or membership charges | Streaming, apps, gym, memberships, software |
Fixed versus variable, essential versus discretionary
Tag each category as fixed or variable, and as essential or discretionary. Fixed costs stay the same each month (rent, loan payments). Variable costs change (groceries, gas, dining out). Essential costs are hard to cut without real consequences (housing, insurance, minimum debt payments). Discretionary costs are the levers you can pull quickly (dining out, hobbies, subscriptions).
A category can be both fixed and discretionary (a gym membership) or variable and essential (groceries).
A worked monthly example
Here is how ten real transactions become category totals. Assume a household with take-home pay of $5,000 a month.
| Date | Transaction | Amount | Category |
|---|---|---|---|
| 1st | Rent payment | $1,450 | Housing |
| 3rd | Electric bill | $110 | Utilities |
| 5th | Supermarket | $180 | Groceries |
| 8th | Gas station | $55 | Transportation |
| 12th | Streaming service | $16 | Subscriptions |
| 15th | Restaurant dinner | $70 | Discretionary |
| 18th | Auto insurance | $120 | Insurance |
| 22nd | Credit card minimum | $95 | Debt payments |
| 25th | Transfer to savings | $300 | Savings |
| 28th | Pharmacy copay | $25 | Healthcare |
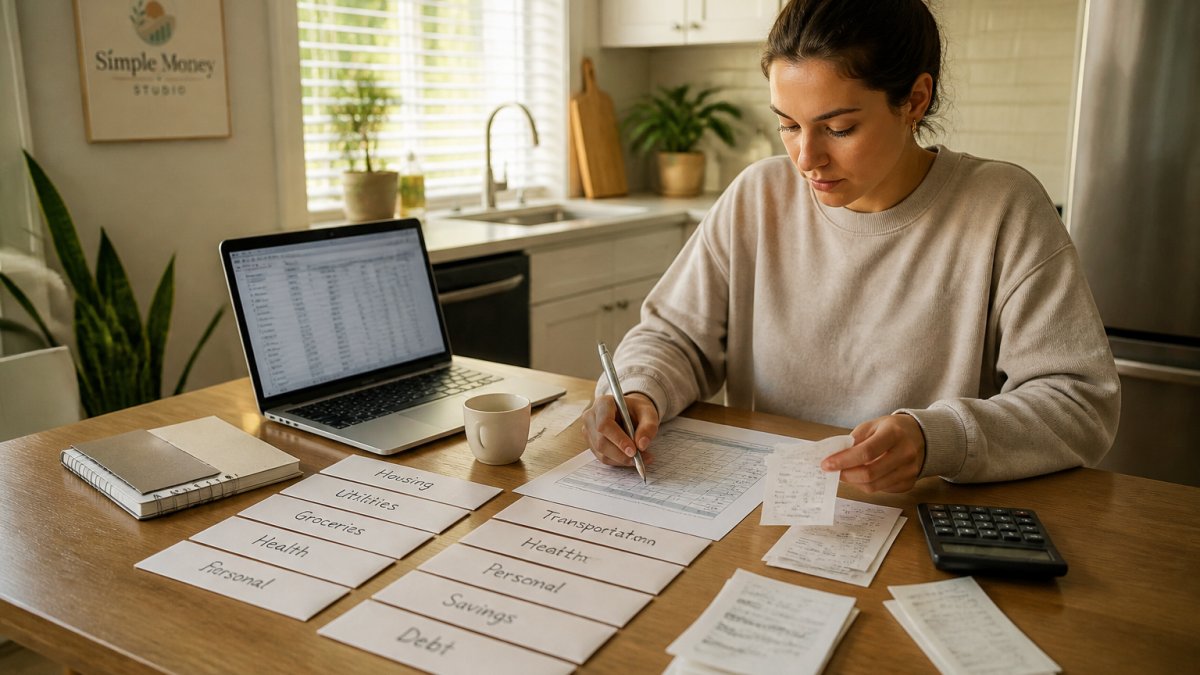
At month end, add the transactions in each category. The totals show the amounts assigned to each category. Here, housing is the largest fixed cost, groceries and transportation are the main variable essentials, and discretionary spending is the smallest lever.
Fixed and Variable Expenses: What Goes Where
Fixed expenses stay the same each month, like rent or a loan payment. Variable expenses change, like groceries, gas, and dining out.
Tag each category as fixed or variable when you set it up.
Building an Irregular Expenses Budget
An irregular expenses budget sets aside money each month for costs that do not arrive on a schedule, like car repairs, annual insurance, or holiday gifts.
List your irregular costs for the year, add them up, and divide by twelve. That monthly figure becomes its own category, a sinking fund you fund on purpose.
If your income itself changes month to month, categories still work, but the plan needs a different rhythm. Our step-by-step guide on how to budget with irregular income covers cash flow and savings when paychecks vary.
Using an Expense Tracking Spreadsheet to Stay Consistent
An expense tracking spreadsheet keeps category assignments in one place so you can see totals without re-adding anything by hand. Paper works too.
A weekly check-in can be used to log the week's transactions and confirm each one has a category.
Choose one payment method for most spending where you can. Fewer accounts means fewer statements to reconcile.
Handling Refunds, Transfers, and Shared Purchases
Refunds, transfers, and shared purchases can be confusing because they may look like income or spending when they are neither. Handle each with one clear rule.
- Refunds: subtract from the original category, not income
- Transfers: exclude entirely, moving money is not spending
- Reimbursements: record the expense, then offset it when repaid
- Shared purchases: log your share only, not the full amount
- Split bills: one category per purchase, not per person
Logging a transfer between your own accounts as income counts the transfer as income. Exclude transfers from day one.
Set Up Your First Expense Categories With the 1-Hour Budget Setup Guide
You now know how to categorize expenses for beginners: list income and bills, pick a starter set, assign every transaction, and review monthly. The last piece is having a format that makes the routine easy to repeat.
Our 1-Hour Budget Setup Guide is a beginner-friendly printable workbook that walks you through four clear steps to build a simple monthly budget in about an hour. It helps you see your income, bills, essential spending, and goals in one place, and find a realistic weekly spending amount.

The Simple Money Studio: Starter Pack includes the budget guide, Money & Bills Organizer, Debt & Savings Tracker, and Subscription Cleanup Planner for $47.96, a $20 savings compared with buying each tool individually.
Frequently Asked Questions
How many expense categories should a beginner have?
Start with 8 to 12 categories. Common starter sets include housing, utilities, groceries, transportation, insurance, healthcare, debt payments, savings, subscriptions, and discretionary spending. You can split a category later if you want to track it separately.
What should I do if an expense fits into more than one category?
Pick the category that best reflects why you spent the money, then stay consistent. Write your rule down so you categorize the same way next month, and review it if the category keeps getting muddied.
How do I categorize irregular expenses like car repairs or annual insurance?
Treat them as their own budget line. Add up last year's irregular costs, divide by 12, and set aside that amount each month in an irregular expenses budget.
How often should I review my expense categories?
Do a weekly check-in to confirm transactions landed in the right place, then a fuller review once a month. After two or three months, look for categories that are too broad or too detailed and adjust.
The hard part of budgeting is not math. It is building a routine you will keep past week three. Simple Money Studio makes that easier with printable tools designed for real life: a four-step budget guide, a monthly bills organizer, and trackers for savings, debt, and subscriptions that all work together. Get started with Simple Money Studio and turn scattered spending into a clear, calm monthly routine.
