

Table of Contents
- Start by Finding Your Overspending Triggers
- How to Control Monthly Expenses With One Simple Review
- Build a Monthly Budget Planner You Will Actually Use
- Use an Expense Tracker Template to Catch Leaks Early
- How to Stick to a Budget When Life Gets Messy
- Set Spending Limits and Digital Controls That Do the Work
- Your Month-by-Month Reset Plan to Stop Overspending
- Conclusion
- Frequently Asked Questions
Last Updated: October 17, 2026
Start by Finding Your Overspending Triggers
Most people try to stop overspending by cutting things randomly. That fails. The better move is to find out why you overspend in the first place. This guide from Simple Money Studio walks you through a simple plan you can start this week.
Overspending is the habit of spending more than your income allows, usually through small, repeated choices rather than one big purchase. It rarely comes from a single decision. It builds from dozens of small ones.
So how do you stop overspending every month? You start with triggers, not spreadsheets.
Common triggers include:
- Browsing online stores when you're bored
- Saving cards in your phone for one-tap checkout
- Shopping while stressed, tired, or hungry
- Saying yes to plans without checking your balance
- Buying things to match what friends or coworkers have
For the next seven days, write down each unplanned purchase and what you were feeling right before it. A common mistake is skipping this step because it feels slow. In practice, this is the fastest way to see your pattern.
Spot the Difference Between Needs and Wants
A need is something required to live and work: rent, groceries, utilities, transport, medication. A want is everything else.
The line moves. A basic phone is a need for most jobs. The newest model is a want. Groceries are a need. Takeout four nights a week is a want wearing a need's clothes.
Try this test before any purchase over a set amount:
- Would my month break without this?
- Do I already own something that does the job?
- Would I still buy it at full price, in cash, tomorrow?
Two "no" answers mean wait 48 hours.
How to Control Monthly Expenses With One Simple Review
You can control monthly expenses with a single 30-minute review each week. That's it. One sitting, one list, one decision.
Pick a fixed time. Sunday evening works for most people. Open your banking app and your bills, then answer three questions:
- What came in this week?
- What went out?
- What's left before the next paycheck?
That's your cash flow in plain numbers. No app subscription needed.
Read Your Bank Statements Like a Detective
Pull the last two statements and read them line by line. You're looking for three things:
- Repeat charges you forgot about
- Small leaks that add up, like delivery fees and app purchases
- Spikes in one category compared to last month
Mark each charge as essential, nonessential, or unsure. The "unsure" pile is where most people find money. According to the Consumer Financial Protection Bureau's guide to tracking spending, reviewing transactions regularly is one of the most reliable ways to spot problems early.
Build a Monthly Budget Planner You Will Actually Use
A monthly budget planner is a written plan that assigns every dollar of income to a category before you spend it. The best planner is the one you'll open twice a week, not the fanciest one.
Most people quit budgeting because their plan is too detailed. Twenty categories is a trap. Start with five:
| Category | What It Covers | Example Share of Income |
|---|---|---|
| Housing | Rent or mortgage, utilities | Largest fixed cost |
| Food | Groceries, basic household | Fixed weekly amount |
| Transport | Gas, transit, insurance | Fixed monthly amount |
| Bills & debt | Phone, subscriptions, minimum payments | Fixed monthly amount |
| Flexible | Fun, eating out, shopping | Whatever is left |
Fill in your own numbers. The point is that every category has a limit before the month starts.
If paper works better for you than an app, our 1-Hour Budget Setup Guide walks you through building this in about an hour. It covers income, bills, a safe weekly spend, and what goes to savings or debt.

Use an Expense Tracker Template to Catch Leaks Early
An expense tracker template is a simple sheet where you log spending by category so gaps show up before they become problems. The goal isn't perfect records. It's catching leaks in week two instead of week four.
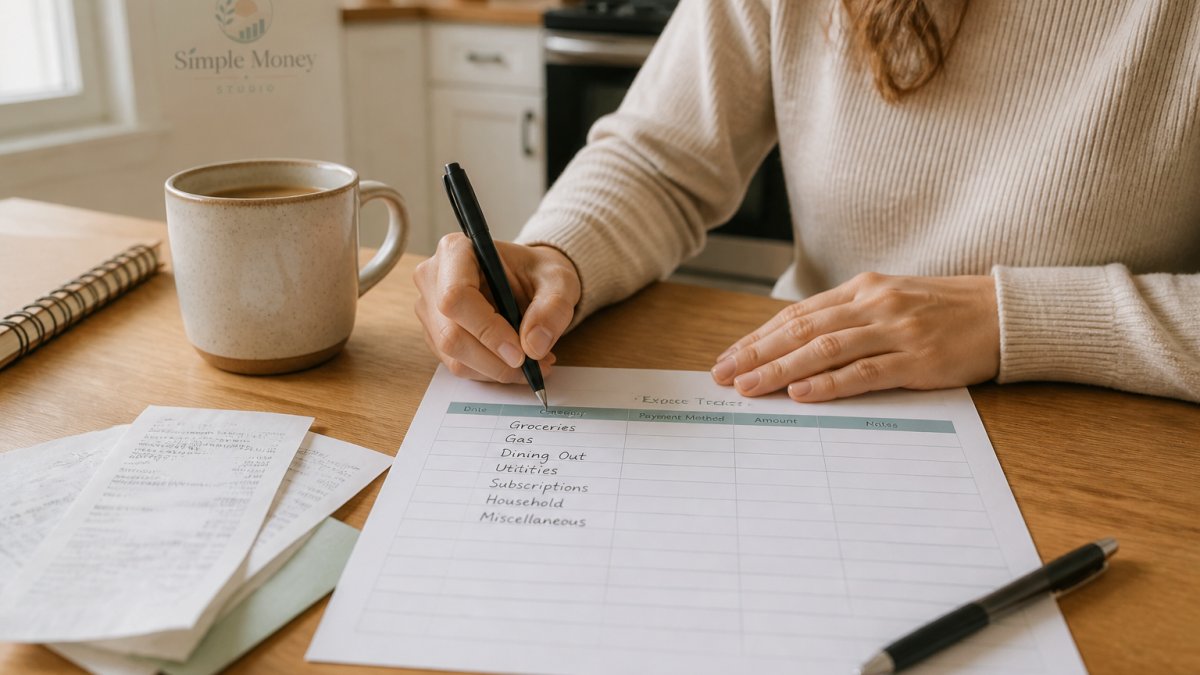
Log spending twice a week. Ten minutes is enough. Then look for one category that's running hot and adjust it.
What most guides miss is that tracking without a weekly review changes nothing. The review is the whole point.
How to Stick to a Budget When Life Gets Messy
You stick to a budget by building slack into it, not by being perfect. Life will send car repairs, medical bills, and last-minute invitations. A plan with no room for those breaks on contact.
Build two buffers:
- A small buffer inside your flexible category for surprises
- A separate savings cushion for bigger hits
When you blow a category, don't abandon the month. Move money from flexible spending and keep going. A budget you return to after a bad week beats one you quit.
Plan for Irregular Income and Surprise Bills
If your income changes month to month, budget from your lowest recent month, not your best. Everything above that baseline goes to savings or debt first.
For annual and quarterly bills, list them with their due months and set aside a slice each month. Our Money & Bills Organizer gives you one page for income, due dates, payments, and notes, plus a five-minute weekly check-in routine.

Set Spending Limits and Digital Controls That Do the Work
Willpower fails at 11pm with a phone in your hand. So remove the decision. Set limits and let your tools enforce them.
Work through these in order. Each one takes minutes and stacks on the last.
1. Remove stored payment methods. Delete saved card details from shopping apps, browsers, and retailer accounts.
2. Turn off one-click and auto-fill. In browser settings, disable autofill for card numbers and turn off "save card" prompts.
3. Cut the cues. Unsubscribe from store emails, turn off push notifications from shopping apps, and unfollow brand accounts on social media.
**4.
**5.
6. Add a purchase delay. For any nonessential purchase over your set amount, use a 48-hour rule: write it down, wait two days, then decide.
**7. Our Subscription Cleanup Planner gives you a page to list every recurring charge, decide what to keep, reduce, pause, or cancel, and track what you free up each month.

If debt is the bigger weight, the Debt & Savings Tracker lets you pick a snowball or avalanche payoff method and watch progress fill in month by month.
Your Month-by-Month Reset Plan to Stop Overspending
Here's the part most plans skip: a sequence. Trying to fix everything in week one is why people quit. Spread it across three months, with one weekly action and one checkpoint per week.
Month 1: See clearly.
- Week 1: Log every unplanned purchase and the trigger behind it. Checkpoint: you have at least five entries with a feeling or situation noted.
- Week 2: Read two months of bank statements line by line. Checkpoint: you have a list of repeat charges, small leaks, and one category that spiked.
- Week 3: List every subscription and recurring charge with amount and renewal date. Checkpoint: every recurring charge is marked keep, reduce, pause, or cancel.
- Week 4: Set up five budget categories and assign a limit to each. Checkpoint: every dollar of income has a category before the month starts.
Month 2: Cut and cap.
- Week 5: Cancel or pause the subscriptions you marked cancel. Checkpoint: you have a confirmed cancellation or a date before the next charge.
- Week 6: Set spending limits on flexible categories and move that amount to a separate account or card. Checkpoint: the flexible balance is separate from your bill money.
- Week 7: Remove saved cards, turn off one-click checkout, and cut store emails and push alerts. Checkpoint: a test purchase now requires typing a card number.
- Week 8: Start the weekly 30-minute review and hold it at a fixed time. Checkpoint: you have completed two reviews in a row.
Month 3: Build and protect.
- Week 9: Set up a small emergency cushion in a separate savings account. Checkpoint: the account exists and has a first deposit.
- Week 10: Automate a transfer to savings on payday. Checkpoint: the transfer is scheduled, not manual.
- Week 11: Plan annual and quarterly bills into monthly set-asides. Checkpoint: each known annual bill has a monthly slice assigned.
- Week 12: Do a monthly review and adjust one thing. Checkpoint: you can name the one change you made and why.
When you blow a category, don't abandon the month. Move money from flexible spending, note the trigger, and keep going. A budget you return to after a bad week beats one you quit.
When income can't cover essentials, stop trying to budget your way out and act in this order: cover housing and food first, contact lenders about payment options before you miss a payment, and look into local assistance programs. Budgeting helps most when there's a gap to close, not when the math doesn't work at all.
Measure progress with three numbers: unplanned purchases per week, flexible spending versus its cap, and money moved to savings. If two of three improve, you're winning. Review the three numbers at the end of each month and adjust one limit, not all of them.
Conclusion
The hardest part of money management isn't math. It's starting when you feel behind. Pick one step from month one and do it this week, then let the routine carry you.
At Simple Money Studio, we build beginner-friendly printables that make this practical: a budget guide you can finish in about an hour, a bills organizer for your monthly routine, and trackers for subscriptions, savings, and debt. Get started with Simple Money Studio and turn a messy month into a plan you can actually follow.
Frequently Asked Questions
How do I identify what is causing me to overspend each month?
Look at three months of bank and credit card statements and highlight every charge that was not planned. Group them into categories like takeout, subscriptions, or impulse purchases. Most people find two or three repeat offenders. Once you can name the pattern, you can set a specific spending limit for that category instead of trying to cut everything at once. A weekly review of your statements makes the pattern obvious faster than a once-a-year glance.
Can an expense tracker template really help me stop overspending?
Yes, because it makes spending visible. When you write down each purchase, unplanned spending becomes harder to ignore. A printable expense tracker template kept somewhere you see daily, like the fridge or a desk, works well for people who forget to open apps. Pair it with a short weekly review so you catch overspending while there is still time to adjust the rest of the month.
How can I stick to a budget when unexpected expenses come up?
Build a small buffer category into your monthly budget planner before the month starts, even $50 to $100. When a surprise bill hits, it comes out of that buffer instead of wrecking the whole plan. For bigger emergencies, pause nonessential spending for two weeks and revisit your savings goal. A budget that expects surprises is easier to stick to than one that assumes a perfect month.
How can couples or families manage spending together without constant arguments?
Agree on spending limits for shared categories like groceries and eating out, and give each person a small no-questions personal amount. Review the budget together once a week for about 10 minutes using the same tracker so you are looking at the same numbers. Shared visibility reduces blame because you are solving a problem together, not auditing each other.