

Last Updated: October 25, 2026
Quick Summary
Zero based budgeting is a spending plan where income minus expenses equals zero, so every dollar gets a job before the month begins. You assign all income to categories including savings and debt repayment, and if money is left over, you keep assigning until the total hits zero.
- Gather 30 to 60 days of bank transactions, bills and paycheck amounts before you start.
- Budget from your after-tax paycheck, not your gross pay, when planning income.
- Divide a semester aid refund by the months it must cover and transfer only the monthly portion.
- Handle lumpy costs like textbooks with a sinking fund, such as $100 a month for a $300 bill.
- When you overspend a category, move money from another the same day so the total stays at zero.
Table of Contents
- Why Zero Based Budgeting Fits Student Life
- How to Make a Zero-Based Budget in Seven Steps
- A Zero-Based Budget Example for Students
- Budgeting With Irregular Income and Financial Aid
- Student-Specific Expense Planning: Textbooks, Housing, and Spring Break
- Choosing a Student Budget Template That Sticks
- When You Overspend: Adjusting the Plan Without Quitting
- Start Your First Zero-Based Budget This Week
- Frequently Asked Questions
Why Zero Based Budgeting Fits Student Life
Most student budgets fail because they leave money unassigned, which is exactly the problem zero based budgeting solves. A zero-based budget is a spending plan where income minus expenses equals zero, so every dollar gets a job before the month begins.
Student income arrives in odd chunks: a paycheck here, a refund there, family help when things get tight. A zero-based spending plan handles that chaos because it does not assume a steady salary.
The Income Minus Expenses Equals Zero Formula
Zero means fully assigned, not fully spent. If you bring in $1,400 this month, you assign $1,400 to categories: rent, groceries, gas, phone, savings, debt repayment, and a small buffer for fun. If categories total $1,250, you still have $150 to place.
Traditional budgets limit a few categories and let the rest drift. Zero-based budgeting assigns every dollar a purpose, including savings and debt repayment, so nothing quietly disappears into takeout and rideshare charges.
How to Make a Zero-Based Budget in Seven Steps
Here is the repeatable process we recommend. It takes about an hour the first time and much less after that.
- Gather your numbers. Pull the last 30 to 60 days of bank transactions, your bill list, and your paycheck amounts.
- List every income source. Paychecks, side gigs, financial aid refunds, family help. Convert weekly or biweekly pay into a monthly figure.
- List fixed expenses first. Rent, phone, insurance, subscriptions, minimum debt payments. These are the same every month.
- Estimate variable expenses. Groceries, gas, laundry, personal care. Use your actual recent spending, not a guess.
- Subtract expenses from income. If the result is positive, you have money left to assign. If negative, cut before you spend.
- Assign the remainder. Send what is left to savings, debt payoff, and a small spending cushion until the total hits zero.
- Track and review monthly. Compare planned versus actual spending and adjust next month's plan.
List Income, Then Fixed and Variable Expenses
Order matters. Income first shows the real ceiling for the month. Fixed expenses come next, because rent and your phone bill are not negotiable. Variable expenses follow, and this is where students find the leaks: food delivery, streaming add-ons, and impulse buys that never felt like real spending. A simple expense tracker for students makes it easy to record and categorize that spending as you go.
A Zero-Based Budget Example for Students
Most budgeting examples use a steady salary and household bills. Student money does not work that way.
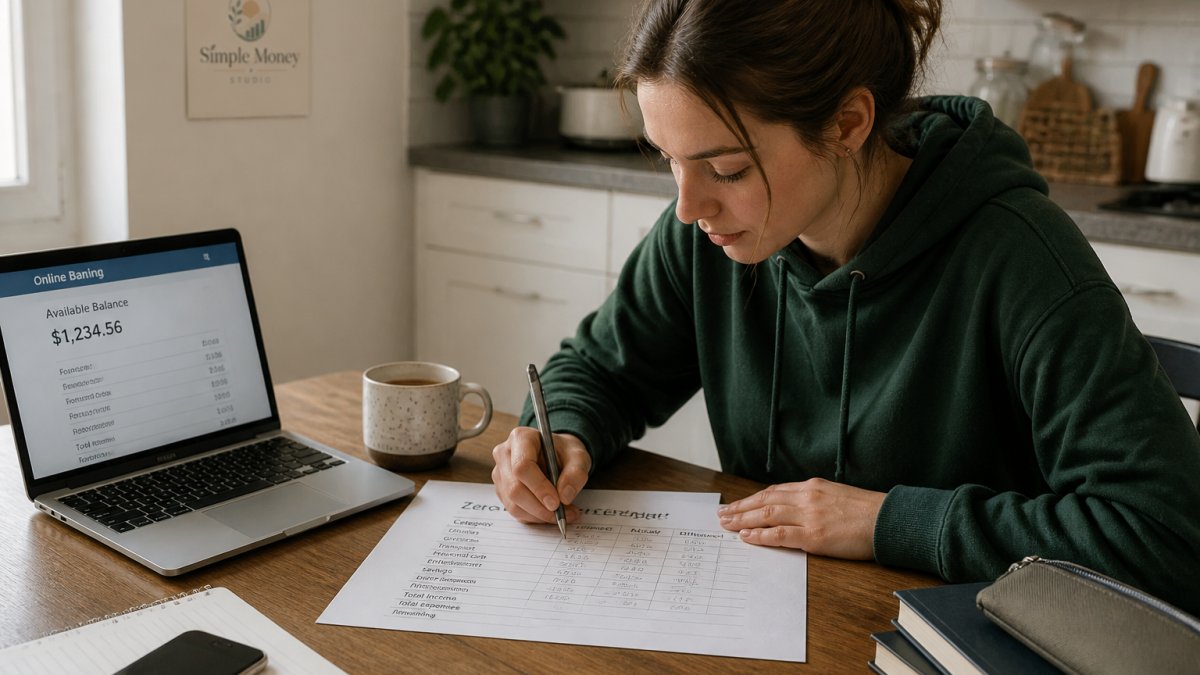
The setup. A student shares a two-bedroom apartment with two roommates. Rent is $1,650 total, so the student's share is $550. Utilities and internet run about $90 per person.
| Category | Amount | Type | Notes |
|---|---|---|---|
| Rent share | $550 | Fixed | Split three ways |
| Utilities and internet | $90 | Fixed | Split three ways |
| Phone | $35 | Fixed | Prepaid plan |
| Groceries | $240 | Variable | About $60 per week |
| Meal plan top-up | $40 | Variable | Only if campus dining is short |
| Gas and transit | $80 | Variable | Bus pass plus occasional gas |
| Books and supplies | $60 | Sinking fund | $240 per semester divided by 4 |
| Personal and laundry | $55 | Variable | Laundry, toiletries, haircuts |
| Subscriptions | $20 | Fixed | One streaming service |
| Savings buffer | $100 | Goal | Emergency fund |
| Debt payment | $50 | Goal | Student loan interest or card minimum |
| Fun and buffer | $60 | Variable | Eating out, events |
| Total assigned | $1,380 | Zero left |
How the aid refund fits. The $2,400 refund is not free spending money.
How the paycheck fits. Budget from the $780 after-tax paycheck, not the $900 gross.
What this example is not. These numbers are illustrative, not universal.
Budgeting With Irregular Income and Financial Aid
Irregular income is why many students abandon budgeting. Part-time hours swing with the academic calendar, gig work arrives in bursts, aid refunds land once per semester, and summer earnings must cover months with no paycheck. A fixed monthly plan built for a salaried worker will not survive that. The fix is a semester-aware plan with a repeatable monthly workflow.
Budget the academic year, not just the month
Map the year into blocks: fall semester, winter break, spring semester, summer. For each, write down the income you can reasonably count on and the costs that land there. Fall and spring usually carry tuition, fees, books, and housing deposits.
Set your baseline monthly plan from the leanest block, not the richest. Build essential categories, rent share, utilities, groceries, transit, phone, around that baseline.
Treat each aid disbursement as a semester budget
A financial aid refund is not monthly income. It is a semester-sized sum covering semester-sized costs. When it hits your account, do three things before spending any of it:
- Subtract the costs it is meant to cover. If the refund is intended for housing or books, move those amounts to a separate account or category first.
- Divide the remainder by the months it must last. A refund that must cover four months gets divided by four. A refund that must cover a summer term gets divided by the number of months in that term.
- Transfer only the monthly portion into checking. Keep the rest in a savings account so it is not visible to daily spending.
This is the single most effective habit for students on aid: it converts a lump sum that feels large into a monthly number that matches your plan.
Build a simple monthly workflow
A budget only works if you run it. Here is a repeatable routine that takes about 20 minutes a month:
- Day 1 of the month: confirm income that has actually arrived, not income you expect. Adjust the plan if a paycheck or refund is late.
- Week 1: assign every dollar to a category until the total hits zero. Include savings and debt payments as categories, not leftovers.
- Mid-month check: compare planned versus actual spending in your two or three biggest variable categories, usually groceries, eating out, and transit. Move money between categories the same day if one is running hot.
- End of month: note which categories were wrong and why. Fix the estimate for next month rather than promising to be more disciplined.
Plan for the lean months before they arrive
Summer and winter break are where irregular-income budgets break. If July will have fewer shifts, start assigning a small amount to a summer buffer in March. Even $50 a month from March through June creates a $200 cushion for groceries or a utility bill when work slows.
If your income swings a lot, a deeper walkthrough on how to budget with irregular income covers the mechanics in more detail.
Student-Specific Expense Planning: Textbooks, Housing, and Spring Break
Some student costs do not fit a normal monthly budget because they land in lumps. Textbooks arrive in one brutal week. Housing deposits come due before the semester starts.
Handle these with a sinking fund. Divide the expected cost by the months until you need it and assign that amount monthly.
Watch out: annual and one-time costs are the single most common reason student budgets collapse mid-semester.
Choosing a Student Budget Template That Sticks
The best budget format is the one you will actually open. Apps work for some people. Paper works better for others, especially anyone who finds complex finance apps overwhelming or forgets to check a screen.
A printable budget worksheet has one advantage apps rarely match: it is visible. Tape it inside a notebook or on a desk, and the plan stays in front of you instead of buried behind notifications. Comparing printable budget templates side by side helps you choose one before committing.
When You Overspend: Adjusting the Plan Without Quitting
Overspending does not mean the budget failed. It means a category was set wrong. The worst response is abandoning the plan entirely, exactly what happens to most people in week three.
When you blow a category, move money from another the same day, $40 from fun into groceries. For practical tactics to stop overspending next month, see how to stop overspending every month.
A budget is a plan you revise, not a test you pass or fail.
Start Your First Zero-Based Budget This Week
You do not need perfect numbers to start. You need one hour, your recent transactions, and a willingness to write down what is actually happening with your money.
This is where we can help. Our 1-Hour Budget Setup Guide walks you through building a working monthly budget in about an hour, using a four-bucket framework: income, bills, weekly spending, and savings or debt goals.

Get started with Simple Money Studio and turn your income into a plan where every dollar has a place.
Frequently Asked Questions
What is zero-based budgeting, in plain terms?
Zero-based budgeting is a spending plan where income minus expenses equals zero. Every dollar gets a purpose before the month starts: rent, groceries, gas, savings, debt payments, and a small fun category. The zero does not mean you spend everything; it means nothing is left unassigned. Money you send to savings or debt counts as assigned, so the plan still balances to zero while you build an emergency fund.
How do students create a zero-based budget when income changes every month?
Use your lowest expected monthly income as the base plan, then assign any extra paychecks when they arrive. List fixed expenses first (rent, phone, insurance), then essentials like groceries and gas, then goals. When a side gig or refund lands, give that money a job immediately: extra debt payment, savings, or next month's buffer. Budgeting with irregular income works as long as you plan from the floor, not the best month.
Can financial aid and scholarships fit into a zero-based budget?
Yes. Treat each disbursement as income for the semester it covers, then divide it across the months it must last. Tuition and fees are fixed expenses, while books, housing, and meal money are variable. If a refund hits your account in one lump, assign portions to each month's categories so it does not disappear by October. Review the plan at the start of every semester as aid amounts and costs change.
What is a realistic zero-based budget example for a student?
A student with $1,800 monthly income might assign $700 to rent, $250 to groceries, $120 to utilities, $80 to phone, $100 to gas or transit, $60 to textbooks, $150 to savings, $100 to debt, and $240 to discretionary spending. That totals $1,800, so the plan balances to zero. Adjust the amounts to your actual numbers; the structure matters more than the exact figures.
How often should students review a zero-based budget?
Do a five-minute weekly check to confirm bills are paid and spending is on track, then a fuller review at the end of each month. Update the plan whenever income changes, a new semester starts, or an unexpected cost appears. A printable student budget template makes these check-ins quick because you can see expected income, actual spending, and what still needs adjusting on one page.
The challenge is not math. It is starting. Set aside one hour this week, gather your numbers, and assign every dollar a purpose. Our printable workbooks at Simple Money Studio are built to make that first budget simple, visible, and repeatable, with a four-bucket framework, a monthly bill organizer, and a savings and debt tracker that shows your progress month by month. Get started with Simple Money Studio and build a budget you will actually keep using.
