

Table of Contents
- What a Paper Financial Planner Does for Debt Payoff
- How to Make a Debt Payoff Plan Using Paper Tools
- Understanding Debt Snowball Worksheet Strategies
- Paper Budget Planner vs Spreadsheet: Which Wins for Debt
- The Real Cost-Benefit: Paper Planner Investment
- When a Paper Financial Planner Actually Works
- When Digital Tools Make More Sense
- Frequently Asked Questions
Last Updated: October 11, 2026
What a Paper Financial Planner Does for Debt Payoff
A paper financial planner debt payoff tool is a printable workbook that helps you track, organize, and systematically pay down debt using pen and paper instead of apps or spreadsheets. Paper planners give you a tangible way to see your debt balances, choose a payoff strategy, and monitor your progress month by month, without the distraction of notifications or complexity of financial software.

The core job is simple: hold you accountable. When you write down your debt balances, monthly payments, and progress bars by hand, something shifts. The information sits right in front of you, updated monthly, visible enough to stay top of mind.
Paper planners include spaces for listing each debt with its balance, interest rate, and minimum payment. They guide you to choose between the debt snowball method (paying off smallest balances first for quick wins) or the debt avalanche method (tackling highest interest rates first to save money overall). Then they provide a month-by-month tracker with progress bars, visual proof that your efforts are working.
How to Make a Debt Payoff Plan Using Paper Tools
Creating a debt payoff plan on paper takes about 30 minutes. Start by listing every debt you have, credit cards, personal loans, medical bills, student loans, with the current balance, interest rate, and minimum monthly payment for each.
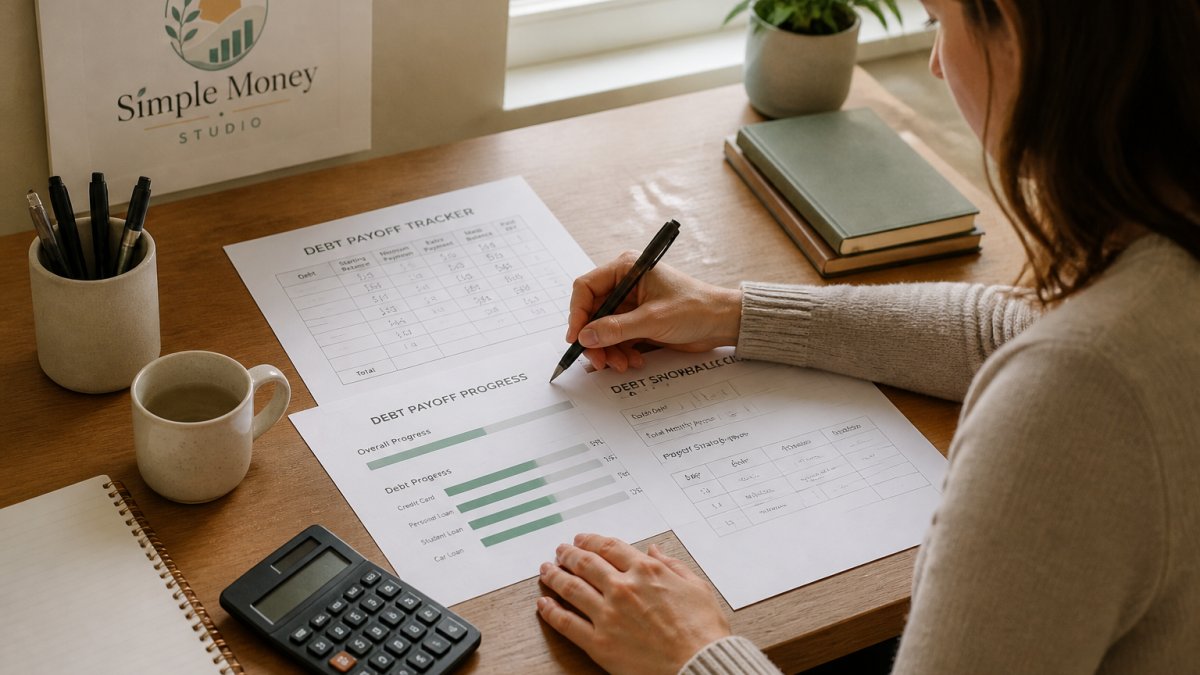
Next, decide which payoff strategy fits your situation. The debt snowball focuses extra payments on your smallest balance first. You pay minimums on everything else, then attack the smallest debt aggressively. Once it's gone, you roll that payment into the next smallest debt. This method builds momentum and delivers quick wins.
The debt avalanche targets your highest interest rate first. You pay minimums on everything, then send extra money toward whichever debt costs you the most in interest. This saves the most money overall, but progress feels slower because high-interest debts often carry larger balances.
Write your choice directly on the planner. Then decide: how much extra can you send toward your target debt each month? Be realistic. A paper planner forces this honesty because you're writing it down by hand.
Finally, set a target payoff date. Write it on your planner. Seeing a specific finish line, not just "someday", changes how you approach the work.
Understanding Debt Snowball Worksheet Strategies
The debt snowball worksheet organizes your debts by balance, smallest to largest, then guides you to focus your extra payments on the smallest one. This strategy works because it delivers visible progress fast and creates momentum to stick with the entire plan.
For example: with a $500 credit card, $3,200 personal loan, and $8,000 car loan, the snowball targets the credit card first. You pay minimums on the others, then send every extra dollar toward the card. Once it's gone, you roll that payment into the personal loan, then the car loan.
The psychological win matters more than people realize. Paying off one debt in months instead of years builds belief that the whole plan is possible and keeps you going through harder, longer debts.
The drawback is that the snowball ignores interest rates. You may pay more in total interest by attacking the small one first. But the motivation works for you. Choose based on what will actually keep you going.
Paper Budget Planner vs Spreadsheet: Which Wins for Debt
A paper budget planner and a spreadsheet are fundamentally different tools. The spreadsheet wins on flexibility and automatic calculations. You can sort debts by interest rate, run "what-if" scenarios, and generate charts instantly.
But the paper planner wins on consistency and friction. When you open a spreadsheet, email, calendar, and social media are one click away. With paper, you sit down, open the planner, pick up a pen, and there's nothing else to do. The friction is actually its strength for debt payoff.
Paper also creates a physical record you can't accidentally delete. Spreadsheets can corrupt, get overwritten, or vanish if you lose access to your account. A printed planner sits on your desk as tangible proof of your progress.
The real difference comes down to behavior. Spreadsheet users often set up an elaborate system, use it for three weeks, then abandon it. Paper planner users develop a ritual: update the tracker monthly, look at the progress bars, feel the progress. The simplicity forces consistency.
| Aspect | Paper Planner | Spreadsheet |
|---|---|---|
| Setup Time | 5-10 minutes | 30-60 minutes |
| Monthly Update Time | 5-10 minutes | 5-15 minutes |
| Distraction Risk | Low | High |
| Flexibility | Medium | High |
| Durability | Permanent | Cloud-dependent |
| Best For | Consistency-focused | Math-focused |
The Real Cost-Benefit: Paper Planner Investment
A paper financial planner typically costs between $16.99 and $18.99 as a standalone tool, or $47.96 for a complete bundle that includes budget setup, bill tracking, and subscription cleanup alongside debt payoff. The Debt & Savings Tracker from Simple Money Studio runs $16.99 as a one-time purchase. You print it at home and reuse it month after month for your own finances.

Compare that to a monthly subscription app at $10-20 per month. Over two years, the typical debt payoff timeline, you're spending $240-480. The paper planner costs less than one month of most subscription services and you own it forever.
But the real cost-benefit isn't about money. It's about whether the tool actually changes your behavior. If a $17 paper planner keeps you accountable and helps you pay off $15,000 in debt, the ROI is extraordinary. If an app subscription doesn't change your behavior, it's wasted money.
Upfront Cost vs Long-Term Value
The upfront cost of a paper planner is negligible compared to the long-term value if it works. You're buying a tool that requires no subscription, no login, no app update, and no recurring charge. Print it, use it, reprint it next year if you need a fresh copy. The barrier to getting started is lower than almost any alternative.
The long-term value depends entirely on whether you'll actually use it. If you get overwhelmed by too many notifications and options, a paper planner might be exactly what breaks through the noise.
Many people find that combining tools works best: a paper planner for the monthly ritual and visual progress, paired with a simple spreadsheet or app for tracking daily expenses if needed. The paper planner becomes the accountability tool; the app becomes the detail tool.
Behavioral Benefits of Writing by Hand
Writing by hand activates different parts of your brain than typing. When you write your debt balances and progress by hand, you're processing the information more deeply and engaging with it deliberately.
Research from Princeton University's study on note-taking found that handwriting engages deeper processing than typing, leading to better retention and understanding. For debt payoff, that means you're more likely to remember your balances, your target date, and your progress. You're building a mental map of your debt situation instead of just glancing at a number on a screen.
The physical act also creates a pause. When you sit down to update your paper planner, you're forced to stop and think about your progress. That reflection is where behavior change happens. Digital tools let you scroll past without thinking. Paper forces attention.
When a Paper Financial Planner Actually Works
A paper financial planner debt payoff system works best for people who struggle with app overload or need a tangible, visible system to stay motivated. If you feel overwhelmed by financial software or need to see your progress physically written down, paper is your answer.
It also works well for people just starting their debt payoff journey and needing something simple to build confidence. A paper planner does exactly that: help you see your debt, pick a strategy, and track your progress.
Paper planners work when you're willing to commit to a monthly ritual. If you can carve out 10 minutes each month to update your tracker, the system stays alive. That consistency builds momentum. People who skip months lose the benefit.
The approach also works for people who want to involve family members in the debt payoff process. A paper planner sits on the kitchen table or desk where everyone can see it. It becomes a visible reminder of the shared goal. Digital apps hide on phones where only one person typically engages with them.
When Digital Tools Make More Sense
Digital tools win when you need flexibility, automatic calculations, or the ability to track daily expenses alongside debt payoff.
Digital also makes sense if you're managing complex debt situations: multiple creditors, variable interest rates, or income that changes monthly. Spreadsheets can automate the math. You update one number and see instantly how it affects your payoff timeline.
Choose digital if you're someone who naturally lives in apps and spreadsheets anyway. If you're already tracking your budget in a spreadsheet, adding debt payoff to that same tool makes sense. You're not adding a new system, you're expanding an existing one.
Digital also works better if you need to share your debt plan with a financial advisor, credit counselor, or partner who prefers digital access. You can email a spreadsheet or share a cloud link. You can't easily share a paper planner unless you photograph or scan it.
The key question: will you actually use it? A sophisticated digital system you abandon beats a simple paper planner every time. But a simple paper planner you use consistently beats a sophisticated system you ignore. Choose based on your actual behavior, not what sounds best in theory.
A paper financial planner for debt payoff is worth it if you struggle with digital overload, need visible progress to stay motivated, or are just starting your debt payoff journey.
Frequently Asked Questions
Is a paper debt payoff planner actually worth the cost?
A paper financial planner is worth it if you struggle with digital distractions or need a tangible way to track progress. The Debt & Savings Tracker costs $16.99 and includes strategy guidance, progress bars, and monthly check-ins designed specifically for debt payoff. The real value comes from consistent use, if writing by hand keeps you accountable, the cost pays for itself through faster payoff. However, if you already use spreadsheets or apps successfully, the paper planner may be redundant.
What should you track in a debt payoff planner?
Track each debt's name, starting balance, current balance, interest rate, minimum payment, and extra payment amount. Include a total of all debt paid off so far and note your chosen strategy (snowball or avalanche). Monthly check-ins should capture total payments made, biggest wins, and challenges. Quarterly summaries help you see three-month progress and adjust your plan. Visual progress bars make the payoff feel real even when balances move slowly.
Should I use a paper planner, spreadsheet, or budgeting app to pay off debt?
Paper planners work best if you avoid digital tools or need tactile feedback. Spreadsheets offer flexibility and automatic calculations but require discipline to update. Apps provide real-time tracking and notifications. Choose based on your habits: if you forget to check apps, paper works better; if you're always on your phone, an app may stick. Many people succeed with paper paired with a monthly budget organizer that keeps everything in one system.
How often should you update a debt payoff tracker?
Update your tracker once a month, ideally on payday or the first of the month. Monthly updates are enough to build momentum without becoming a chore. A quick 5-minute check-in captures new balances, payments made, and progress toward your goal. Quarterly reviews (every three months) help you step back and see the bigger picture, adjust your strategy if needed, and celebrate wins that may feel small month-to-month.