

Table of Contents
- Quick Comparison: Simple Budget Trackers for Families
- How to Choose a Family Budget Tracker
- 1. Simple Money Studio Starter Pack: Complete Printable System
- 2. 1-Hour Budget Setup Guide: Fastest Way to Start
- 3. Money & Bills Organizer: Monthly Home Base
- 4. Debt & Savings Tracker: Visual Progress Tool
- 5. Subscription Cleanup Planner: Free Up Extra Money
- How to Manage Household Expenses with a Simple Budget Tracker
- Frequently Asked Questions
Last Updated: September 23, 2026
Quick Comparison: Simple Budget Trackers for Families
A simple budget tracker for families works best when it fits how your household handles money. This guide from Simple Money Studio compares five printable tools covering budgeting, bills, debt, savings, and subscriptions.
If you have downloaded a budgeting app, entered three weeks of transactions, then quietly stopped opening it, you are not alone. A printable system kept on the counter or in a binder gets used more consistently because it stays visible.
| Tool | Price | Best For | Core Focus |
|---|---|---|---|
| Starter Pack | $47.96 | Families wanting one complete system | Budget, bills, debt, savings, subscriptions |
| 1-Hour Budget Setup Guide | $18.99 | First-time budgeters | Building a monthly budget fast |
| Money & Bills Organizer | $16.99 | Households juggling due dates | Monthly bill tracking and check-ins |
| Debt & Savings Tracker | $16.99 | Families paying down debt | Visual progress on goals |
| Subscription Cleanup Planner | $14.99 | Trimming recurring charges | Auditing and cutting subscriptions |
How to Choose a Family Budget Tracker
Choosing a family budget tracker comes down to four questions: who will open it, how often, what problem it solves first, and what you will pay. Most households need just the one tool that addresses their biggest pain point.

1. Name the first problem. If bills slip through the cracks, start with a bill organizer. If you have never built a budget, start with a setup guide. If debt feels hopeless, start with a progress tracker. Buying a full system before you know your habits is the most common waste of money here.

2. Decide who touches it. A tracker only one partner opens is a solo budget wearing a family label. If both adults need access, the tool needs a shared login, multi-user access, or a physical binder in a common space. If a teenager or grandparent will log expenses, the format must be simple enough to use without a walkthrough.
**3.
- Paper or printable. Lowest cost, no bank connection, no monthly fee, works offline. The trade-off is manual entry and no automatic syncing.
- Spreadsheet. Free or near-free, fully customizable, easy to share through a cloud drive. The trade-off is that a broken formula or a deleted row can quietly corrupt your totals.
- App. Automatic transaction import, alerts, and multi-device sync. The trade-off is a recurring subscription, a bank-linking decision, and the abandonment pattern that hits most families within a few weeks.
Choosing a tracker for a non-traditional household
Most budgeting advice assumes two married adults, one shared checking account, and children in the same home, a shrinking share of actual households. If your situation differs, the criteria change.
Key Features for Household Finance Management
The features that matter most for household finances are shared visibility, a short check-in routine, and clear categories. Look for a tracker that handles:
- Multiple income sources so side gigs and irregular pay are captured
- Bill due dates and payment status in one view
- Shared accounts and multi-user access so both partners can contribute
- Budget categories for fixed and variable expenses
- Recurring bills and subscription management to catch creeping charges
- Progress tracking for savings and debt repayment
Automated syncing and real-time alerts are useful but not requirements. A printable budget planner for families delivers the same clarity without bank-level security concerns or monthly fees.
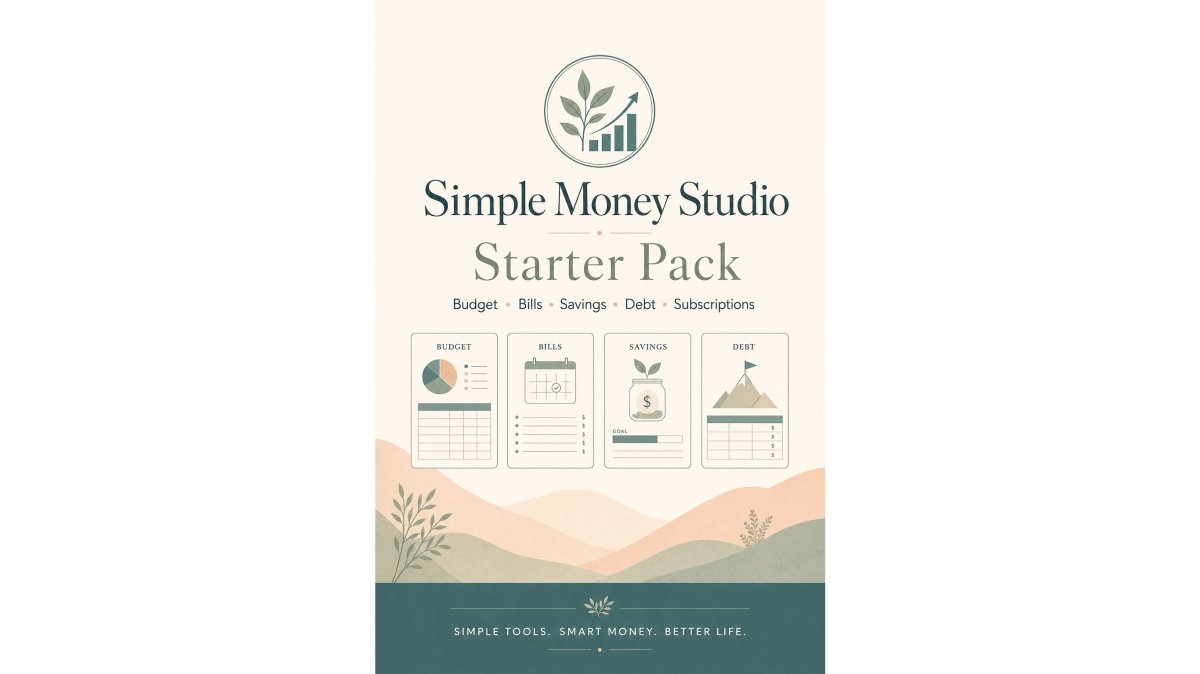
1. Simple Money Studio Starter Pack: Complete Printable System
- 1-Hour Budget Setup Guide for building a monthly budget fast
- Money & Bills Organizer for tracking income, bills, and due dates
- Debt & Savings Tracker for watching progress on goals
- Subscription Cleanup Planner for cutting recurring charges
Pros: One purchase covers budgeting, bills, debt, savings, and subscriptions. Reusable month after month. Beginner-friendly.

2. 1-Hour Budget Setup Guide: Fastest Way to Start
Pros: Fast, realistic, and built for beginners. Includes fillable worksheets and examples.
3. Money & Bills Organizer: Monthly Home Base
The Money & Bills Organizer is your monthly dashboard. It tracks total income, bills due, bills paid, and bills still due in one place, and it costs $16.99.
4. Debt & Savings Tracker: Visual Progress Tool
The Debt & Savings Tracker turns payoff and savings goals into something you can see. It costs $16.99.
5. Subscription Cleanup Planner: Free Up Extra Money
Pros: Fast to complete. Makes savings visible. Repeatable as a yearly routine.
How to Manage Household Expenses with a Simple Budget Tracker
Managing household expenses starts with one rule: make the system smaller than your patience for it. Families that track everything usually stop tracking anything. A workable routine: set up your budget once, run a five-minute weekly check-in on bills, update savings and debt monthly, and run a subscription audit once or twice a year. The rest of this section covers the part most guides skip, the people using it.
The weekly check-in, in detail
Pick a fixed time, Sunday evening and Monday morning are the two most common. The check-in has four steps and takes about five minutes:
Simple Money Studio: Starter Pack →
- Open the monthly overview and confirm what was paid since the last check-in.
- Look at the next seven days and flag anything due.
- Note any expense that surprised you.
- Write one action item for the week.
When partners disagree about money
For couples, the friction is rarely the math. It is usually disagreement about discretionary spending, one partner sees a purchase as reasonable, the other sees it as a leak. A shared, neutral worksheet helps because the numbers make the case instead of one partner making it.
-
Shared fixed costs, rent or mortgage, utilities, insurance, groceries, childcare. Paid from a shared account or tracked on a shared page.
-
Shared goals, savings, debt payoff, a family trip. Funded on a schedule, not on whatever is left over.
-
Personal no-questions money, a set amount each partner can spend without discussion.
-
Agree on the threshold, not every purchase. Decide together what amount requires a heads-up. Below it, no discussion needed.
-
Separate the decision from the emotion. Review the numbers at the scheduled check-in, not in the moment a purchase happens.
-
Use 'we' language on shared goals. 'We are $400 from the payoff' lands differently than 'you spent too much.'
-
Revisit the personal amount quarterly. What felt generous in January may feel tight in July.
Teaching kids financial literacy through the tracker
A family budget tracker is one of the few household tools a child can actually use. Letting a child fill in a savings progress bar teaches the same lesson an app does, with more ownership.
A simple system that works for many families:
- Give each child a labeled savings page with a goal and a target date. A visible goal beats an abstract one.
- Tie allowance or chore pay to a written entry. The child records the amount, the date, and the running total. Writing it down is the lesson.
- Use three jars or three columns, spend, save, give. The split can be simple, like 50/30/20, or whatever your family decides.
- Let them make a small mistake. A child who spends a saved amount on something they regret learns more than one who is told not to.
For households that want a manual, offline method
Many families are wary of linking bank accounts to an app, and that is reasonable. A printable budget worksheet is often easier to keep up than an app, with no subscription, no data-sharing decision, and no risk of a sync error quietly changing your totals. The trade-off is manual entry, which is why the weekly check-in has to stay short.
Frequently Asked Questions
What is a good simple family budget tracker?
A good simple budget tracker for families should be easy to use, cover shared expenses, and help you see progress. The Simple Money Studio Starter Pack includes four printable workbooks: a 1-Hour Budget Setup Guide, Money & Bills Organizer, Debt & Savings Tracker, and Subscription Cleanup Planner. It costs $47.96 and works for households with multiple income sources and shared bills.
Are printable budget trackers better than apps for families?
It depends on your family's habits. Printable trackers like the Money & Bills Organizer give you a physical copy to keep on the fridge or in a binder, which helps some families stay consistent. Apps offer automated syncing but can feel overwhelming. If you prefer hands-on tools and want to avoid subscription fees, a printable budget planner for families is a practical choice.
How do I set up a simple budget for my family?
Start with the 1-Hour Budget Setup Guide. It walks you through four steps: gather your income and bills, list fixed expenses, estimate weekly spending, and assign money to savings or debt. The guide includes worksheets and examples. Most families finish their first budget in about an hour. You can refine it monthly as your income or bills change.
Can a simple budget tracker help with debt repayment?
Yes. The Debt & Savings Tracker helps you choose a payoff strategy (snowball or avalanche), track balances, and see progress with fill-in bars. It includes monthly and quarterly check-ins so you stay motivated. Pair it with the Subscription Cleanup Planner to free up extra money for debt payments. Many users find that seeing visual progress makes it easier to stick with a plan.
How do I manage household expenses with a family budget template?
Use a template that separates fixed expenses (rent, utilities) from variable expenses (groceries, gas). The Money & Bills Organizer has pages for income, bills due, payment logs, and a bill calendar. Set a weekly 5-minute check-in to review what's due and what's been paid. This routine helps you avoid late fees and stay aware of your cash flow.