

Table of Contents
- Why a Printable Savings Goal Tracker Sheet Beats an App
- What to Include on Your Savings Goal Tracker Sheet
- How to Track Savings Goals Without Losing Momentum
- Choosing a Visual Savings Tracker Printable That Fits Your Goal
- Using an Emergency Fund Tracker Printable for Your First $1,000
- Making the Tracker Work When Your Income Changes
- Common Mistakes That Derail Savings Trackers
- Frequently Asked Questions
Last Updated: September 18, 2026
Why a Printable Savings Goal Tracker Sheet Beats an App
A printable savings goal tracker sheet is a paper-based tool that lets you write down a savings target, log each deposit by hand, and watch a progress bar fill up over time. This guide from Simple Money Studio explains how to choose, set up, and stick with one. Many people find that a physical sheet keeps them more consistent than a phone notification they swipe away without thinking.

That's the core argument here: friction works in your favor. An app makes saving effortless, and effortless things are easy to ignore. A sheet you fill in with a pen asks for thirty seconds of attention, and that small ritual is exactly what keeps a goal alive.
Below, we'll show you what belongs on the sheet, how to track savings goals without losing steam, and which layouts suit which goals. But first, here's what most guides get wrong: they treat the tracker as a record of the past. The best ones are a plan for the next deposit.
What to Include on Your Savings Goal Tracker Sheet
A useful tracker covers six fields: goal name, target amount, starting amount, current amount, monthly contribution, and target date. The Consumer Financial Protection Bureau's savings guidance recommends setting a specific dollar target and timeline rather than a vague intention, because a defined goal is far easier to measure.
Two more fields do the emotional work. Add "why this goal matters" and "first action this month." A goal named "Emergency Fund" feels administrative. A goal named "Three months of rent if I lose my job" feels urgent, and urgency is what gets the sheet off the desk.
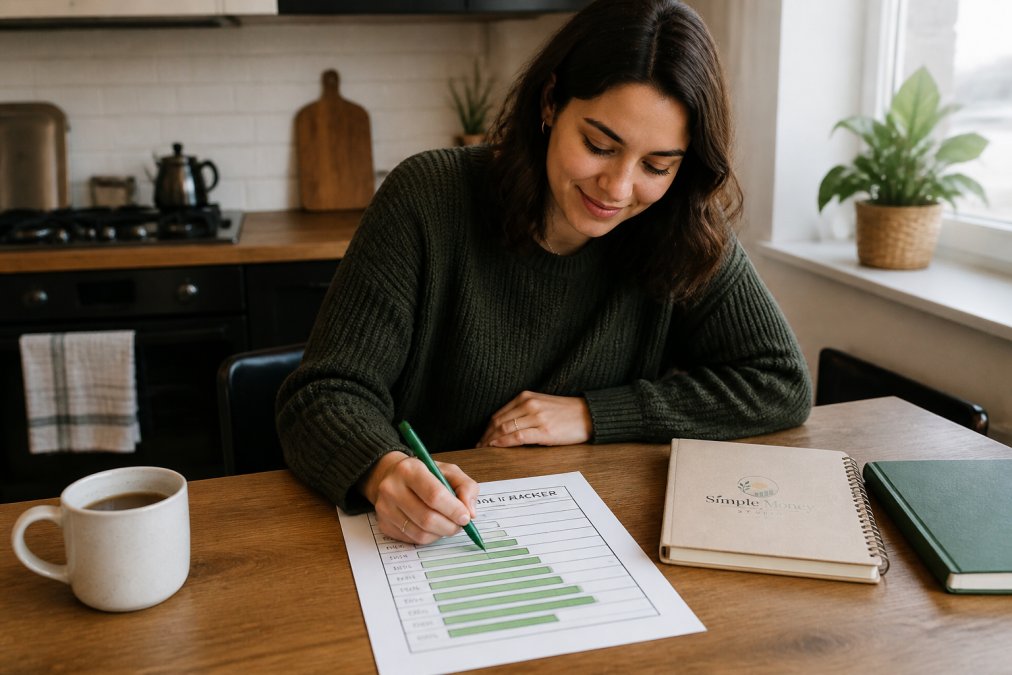
A progress bar matters more than a spreadsheet column. Filling in a bar gives a visible reward that a running total never delivers.
| Field | What to Write | Why It Matters |
|---|---|---|
| Goal name | Specific purpose, not a label | Creates emotional pull |
| Target amount | Exact dollar figure | Makes the finish line real |
| Starting amount | Today's balance | Shows honest progress |
| Monthly contribution | Pencil in an amount | Keeps the plan flexible |
| Target date | Month and year | Creates a deadline |
| Why this matters | One honest sentence | Survives a low-motivation week |
How to Track Savings Goals Without Losing Momentum
Tracking savings goals works when the routine is small enough to survive a bad week. A weekly check-in beats a monthly one, because a month is long enough to forget what you were doing. Pick a fixed moment, such as Sunday morning with coffee, and treat it as part of the week rather than a chore.
Set the Target and the Date
Start with a number you can defend and a date you believe. Divide the target by the number of months, and if the result feels painful, extend the deadline instead of shrinking the goal. A slower plan you finish beats an aggressive one you quit.
Log Every Contribution, Even Small Ones
Log every deposit the day it happens. A five-dollar transfer recorded on time does more for momentum than a fifty-dollar transfer you forget to write down. The habit is the asset, not any single entry.
Choosing a Visual Savings Tracker Printable That Fits Your Goal
A visual savings tracker printable should match the shape of your goal. Short, intense goals need a design that shows progress fast. Long goals need one that rewards patience. Most people pick a layout because it looks nice, then abandon it because it doesn't fit how they actually save.
Here's how to decide:
- Color-in bar: Best for a single goal with a fixed target, like a $1,000 emergency fund.
- Grid or dot chart: Best for goals where you save in small, frequent amounts.
- Milestone tracker: Best for long goals, because it celebrates quarters instead of the finish line.
- Multi-goal sheet: Best when you're saving for two or three things at once.
The mistake most guides miss is choosing a design before choosing the goal. Pick the goal first, then the layout that makes that specific goal feel winnable.
Using an Emergency Fund Tracker Printable for Your First $1,000
An emergency fund tracker printable works best when you break the first $1,000 into milestones rather than staring at one intimidating number. The Federal Reserve's household survey data has consistently shown that a large share of households could not cover an unexpected expense from savings, which is exactly why this first goal matters more than any other.
Split $1,000 into four milestones of $250. Color in a quarter of the bar at each one. Four celebrations in a few months will do more for your consistency than one distant payoff.
Keep this fund separate from your other savings, both in the account and on the sheet. Money with no label gets spent.
Making the Tracker Work When Your Income Changes
Variable income breaks trackers built around a fixed monthly number. The fix is to track percentages and deposits instead of a fixed contribution. On a strong month, log a larger deposit. On a thin month, log whatever you can and keep the streak alive.
Four rules keep a tracker useful when income swings:
- Set the target date, not the monthly amount, as your anchor.
- Log deposits, never missed months.
- Recalculate the monthly figure at the start of each quarter.
- Keep a floor: even a token deposit keeps the habit intact.
This approach suits freelancers, tipped workers, and anyone with side income. The sheet becomes a record of effort rather than a scorecard of failure.
Common Mistakes That Derail Savings Trackers
The biggest mistake is making the tracker too complicated. A sheet with twenty columns gets filled in twice. A sheet with six fields gets filled in for a year.
Other frequent problems:
- Tracking too many goals at once. Three is the practical ceiling.
- Hiding the sheet. If it lives in a drawer, it's already dead. Keep it visible.
- Never reviewing it. A tracker you don't read is a decoration.
- Setting an unrealistic monthly number. Optimism in month one causes quitting in month two.
- Treating a missed month as a failure. It's data. Adjust and continue.
A tracker is a tool, not a verdict. The people who finish their goals are the ones who keep writing in the sheet after a bad month.
Frequently Asked Questions
Are printable savings trackers effective for budgeting?
They work well for people who respond to visible progress. A savings goal tracker sheet sits somewhere you already look, like the fridge or a desk, so every deposit gets marked and the balance stops feeling abstract. The catch is consistency: a tracker only helps if you fill it in. Pairing it with a monthly check-in routine, rather than daily logging, keeps most people from abandoning it after the first week.
What should be included on a savings goal tracker sheet?
At minimum: the goal name, target amount, starting amount, monthly contribution, target date, and a running current balance. Add a progress bar or fill-in shape so the visual matches the number. A short line for why the goal matters helps on months when motivation dips. The Debt & Savings Tracker from Simple Money Studio includes all of these fields plus prompts for your first action each month.
How do I create a simple savings goal tracker?
Pick one goal, write the target amount and date at the top, and divide the total by the number of months you have. That number is your monthly contribution. Draw a progress bar with one segment per month, then shade in a segment each time you deposit. If your income varies, set a minimum contribution instead of a fixed one so you never miss a month entirely.
How can I stay motivated while saving money for a specific goal?
Make progress visible and check in on a schedule. A visual savings tracker printable with fill-in bars turns a slow process into something you can see changing. Monthly and quarterly check-ins, like the ones built into the Debt & Savings Tracker, give you a reason to look at the sheet without obsessing over it daily. Naming the goal specifically, like 'car repair fund' instead of 'savings,' also keeps the reason in front of you.
Saving consistently is less about willpower than about having a system you can see. Simple Money Studio builds beginner-friendly printables for exactly that purpose, including the Debt & Savings Tracker with fill-in progress bars, snowball and avalanche payoff strategies, and monthly check-ins, plus the Starter Pack that bundles budgeting, bills, savings, and subscription tools into one routine. Get started with Simple Money Studio and turn your savings goal into visible, weekly progress.