

Last Updated: October 22, 2026
Quick Summary
Debt repayment motivation is hard to sustain because debt payoff is a slow, quiet process with no visible finish line for months at a time. Your brain discounts distant rewards, gets no feedback loop from payments that barely move the balance, and loses willpower to financial stress. Fix the visibility of progress and most of the motivation problem goes away.
- Shrink your payoff goal until it feels almost too easy, then raise it only after you hit it twice.
- Choose the debt snowball if past payoff attempts died early, or the debt avalanche if you finish plans.
- On low-motivation days, run a ten-minute checklist instead of skipping the month entirely.
- Track on-time payments, interest paid, extra dollars sent, accounts cleared and months kept going.
- After a setback, restart the same week and reset the monthly target to something you can hit.
Table of Contents
- Why Debt Repayment Motivation Fades
- How to Stay Motivated to Pay Off Debt With Small, Realistic Goals
- Debt Snowball vs. Debt Avalanche: Pick the Strategy That Fits You
- How to Pay Down Debt When Motivation Fades
- Make Progress Visible With a Debt Payoff Tracker Printable
- Measuring Progress Beyond the Remaining Balance
- What to Do After a Setback
- When Budgeting Alone Is Not Enough
- Frequently Asked Questions
Why Debt Repayment Motivation Fades
Debt repayment motivation is hard to sustain because debt payoff is a slow, quiet process with no visible finish line for months at a time. This guide from Simple Money Studio explains why the drive fades and how to rebuild it with a system you can actually follow.
Here is the uncomfortable truth most payoff advice skips: you are not lazy. Your brain is doing exactly what brains do when a reward is far away and the effort is daily. Paying $200 extra this month changes almost nothing you can see. So the reward center stops firing.
That mismatch between daily effort and invisible results is the whole problem. Fix the visibility, and you fix most of the motivation.
The Psychology Behind the Drop-Off
Motivation fades for three predictable reasons. None of them are character flaws.
- Delayed reward. Debt payoff pays out months or years later. Your brain discounts distant rewards heavily.
- No feedback loop. A credit card balance barely moves after one payment. No feedback reads as no progress.
- Depletion. Financial stress eats willpower. When you are tired, the budget is the first thing to go.
A common mistake is treating this as a discipline problem. It is a design problem. Change the design and the discipline gets easier.
How to Stay Motivated to Pay Off Debt With Small, Realistic Goals
The fastest way to stay motivated is to shrink the goal until it feels almost too easy. Big payoff targets create big gaps between effort and reward. Small targets close that gap.
Try this sequence:
- Pick one debt and one target for the next 30 days.
- Set a number you are confident you can hit, then cut it by a quarter.
- Write the target where you will see it daily.
- Mark each on-time payment as a win, separate from the balance.
- Review the target every month and raise it only after you hit it twice.
Attainable goals build consistency. Consistency builds momentum. Momentum is what carries you through the months when nothing feels exciting.
We recommend starting with a target so small it feels silly. Hitting it beats missing an ambitious one.
Debt Snowball vs. Debt Avalanche: Pick the Strategy That Fits You
Choosing between the debt snowball and the debt avalanche comes down to one question: do you need quick wins or maximum savings? The snowball targets your smallest balance first. The avalanche targets your highest interest rate first. Both methods assume you pay the minimum on every debt and direct all extra money to one target balance.
| Strategy | What it targets | Best for | Trade-off |
|---|---|---|---|
| Debt snowball | Smallest balance first | People who need momentum and visible wins | May cost more in interest over time |
| Debt avalanche | Highest interest rate first | People who stay motivated by math and savings | Slower to show a cleared account |
The snowball works because of a psychological mechanism called goal gradient effect: people accelerate as they perceive themselves getting closer to a goal (pubmed.ncbi.nlm.nih.gov). Clearing a small balance produces a visible, emotional win that reinforces the habit. The avalanche works because of arithmetic: paying the highest rate first minimizes total interest paid, which can matter a great deal when one balance carries a store card or subprime rate.
A practical way to choose is to look at your own history. If past payoff attempts died in month two or three, the snowball is usually the better bet because it manufactures early wins. If you have stuck with plans before and the interest cost is meaningful, the avalanche is the cheaper path. A hybrid approach also works: use the snowball to clear one or two small balances for momentum, then switch to the avalanche for the remaining high-rate debt, and commit to that switch rather than drifting between methods.
A common mistake is switching strategies every few months. Pick one, commit for at least a quarter, then reassess. The best repayment strategy is the one you will still be running in month eight.
How to Pay Down Debt When Motivation Fades
When motivation fades, stop relying on how you feel and lean on a plan you wrote while you still cared. The goal on a low day is not progress. It is not quitting.
A Low-Motivation Day Plan
Run this short checklist instead of skipping the month entirely:
- Open the tracker and look at one number, not all of them
- Confirm the minimum payments are scheduled
- Send any extra amount, even a small one
- Write one sentence about why this matters
- Close the file and stop thinking about it
That is it. Ten minutes. A low-motivation day handled this way still counts as a win, and the streak stays alive.
Make Progress Visible With a Debt Payoff Tracker Printable
A debt payoff tracker printable is a paper or digital sheet where you log each debt, its balance, and every payment, so progress becomes something you can see rather than something you have to remember. Visibility is the fix for the fading-reward problem.
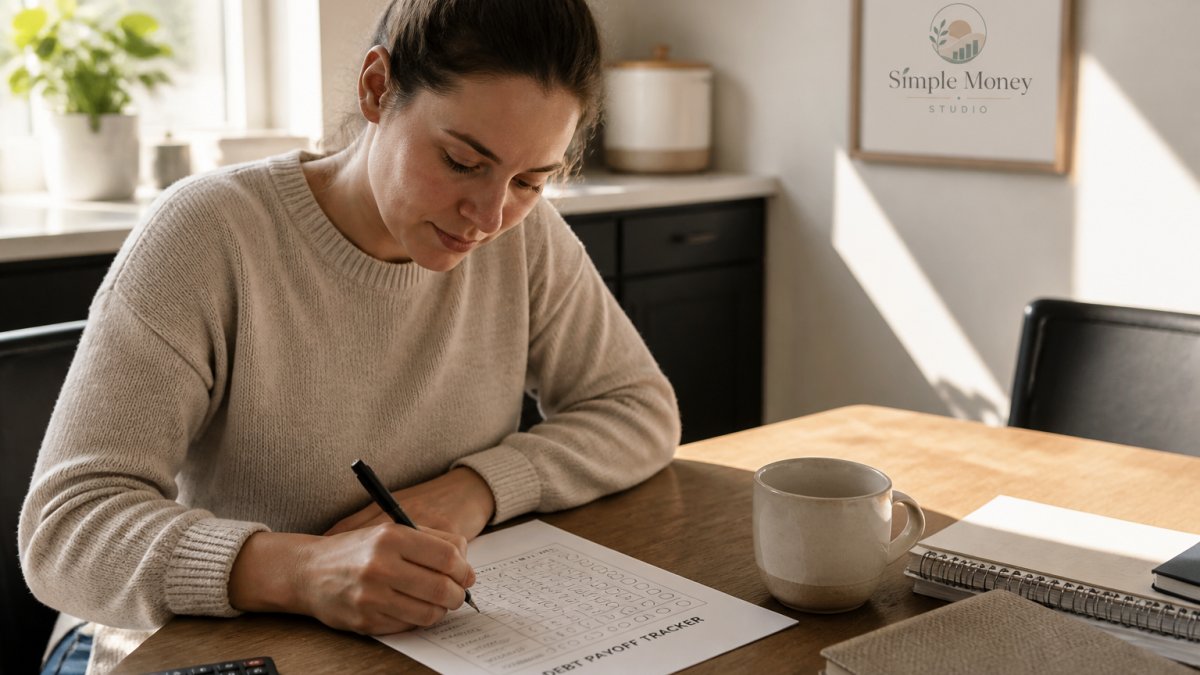
Paper works better than an app for a lot of people. Apps hide the numbers behind taps and tabs. A printed tracker sits on the fridge or desk, and you cannot ignore a fill-in progress bar that has been stuck at the same spot for two weeks.
Our Debt & Savings Tracker is built for exactly this. It includes a payoff strategy page, per-debt balance tracking, and fill-in progress bars for both savings and debt. It also adds monthly and quarterly check-ins, so the habit has a rhythm.

If you have tried apps and found them more complicated than helpful, paper is a fair test. Print one page, fill it in for a month, and see whether the visible progress changes how you feel about the plan.
Measuring Progress Beyond the Remaining Balance
The remaining balance is the worst possible scoreboard, because it moves the slowest. Measure things that change every month instead.
Track these alongside the balance:
- On-time payments. A streak you can protect.
- Interest paid. A number that should trend down.
- Extra dollars sent. Proof of effort, not outcome.
- Accounts cleared. Count them, not just the total.
- Months kept going. The habit itself.
A monthly review of these five takes about ten minutes and tells a truer story than the balance does. When the balance stalls, the streak and the extra payments still move.
What to Do After a Setback
After a setback, the move is to restart the same week, not the same year. Setbacks are normal. Long gaps after setbacks are what wreck payoff plans.
Do this:
- Write down what caused it, in one line.
- Cover the minimum payments first, before anything else.
- Reset the monthly target to something you can hit this month.
- Mark the restart on your tracker so it counts as progress.
- Change one thing in the plan so the same cause is less likely.
If you missed payments and they are now past due, contact the lender before the account goes further. Ask about a payment arrangement. Lenders generally prefer a plan over a default, and getting ahead of it protects your credit.
When Budgeting Alone Is Not Enough
Budgeting alone is not enough when the numbers do not work even at zero spending on extras. That is a math problem, not a motivation problem, and no tracker fixes it.
Watch for these signs:
- Minimum payments exceed what is left after essentials
- You are covering bills with new credit
- Interest is growing faster than you can pay it down
- You have no cushion for a car repair or a medical bill
In those cases, look at options beyond a budget. Nonprofit credit counseling offers low-cost help and is a good first call (What is credit counseling?). Debt management plans, consolidation, and, in serious cases, bankruptcy are worth discussing with a qualified advisor. The Consumer Financial Protection Bureau publishes free guidance on each of these paths.
A budget is still the foundation. It just is not the whole building.
The hardest part of debt payoff is not the math. It is showing up in month seven when nothing feels different. Simple Money Studio builds printable tools for exactly that stretch: our Debt & Savings Tracker makes progress visible, our 1-Hour Budget Setup Guide gives you a working budget in about an hour, and the Starter Pack bundles both with bill and subscription trackers. Start with one page and one month, and let the visible progress do the motivating.


Frequently Asked Questions
Why is it so hard to stay motivated while paying off debt?
Debt payoff is a long, quiet process with few visible rewards. You send the same payment every month and the balance barely moves, so the brain stops registering progress. Add financial stress and the feeling of overwhelming debt, and motivation fades fast. The fix is to make progress visible: smaller payoff goals, a written debt payoff tracker, and monthly check-ins that show movement you would otherwise miss.
How can I stay motivated when paying off debt feels slow?
Break the payoff timeline into small goals you can hit in 30 to 60 days, like paying off your smallest balance or making one extra payment. Track every payment in a debt payoff tracker printable so progress is visible, not just felt. Celebrate milestones, tell an accountability partner about your plan, and review your budget each month. Small, repeatable wins build momentum better than waiting for a big payoff.
Should I use the debt snowball or debt avalanche?
The debt snowball targets your smallest balance first, which delivers quick wins and keeps motivation high. The debt avalanche targets the highest interest rate first, which usually saves more money over time. If motivation is your weak point, the snowball often wins in practice. If you can stay consistent without frequent wins, the avalanche costs less. Either way, pick one strategy and write it down so you are not re-deciding every month.
What should I do when I lose motivation to pay off debt?
Have a low-motivation plan ready before it happens. On those days, do the minimum: confirm on-time payments, log your current balance, and skip the extra payment if needed. Then schedule a short monthly review to check progress and adjust. If a setback hits, restart with one small goal instead of rebuilding the whole plan. Consistency through low-motivation stretches matters more than any single big payment.