

Table of Contents
- Why Visual Budgeting Tools Work for Your Brain
- 1-Hour Budget Setup Guide: Build Your Foundation Fast
- Money & Bills Organizer: See Your Monthly Picture at a Glance
- Debt & Savings Tracker: Make Progress Visible With Charts and Graphs
- Printable Budget Tracker vs. Budgeting Apps: Which Fits Your Style
- Savings Goal Tracker Printable: Watch Your Goals Come to Life
- Get Started With the Complete Starter Pack
- Conclusion
- Frequently Asked Questions
Last Updated: October 8, 2026
Why Visual Budgeting Tools Work for Your Brain
Visual budgeting tools tap into how your brain actually processes information. When you see numbers on a spreadsheet, your mind has to translate them into meaning. When you see a filled-in progress bar or a chart showing your debt shrinking month by month, your brain gets it instantly.
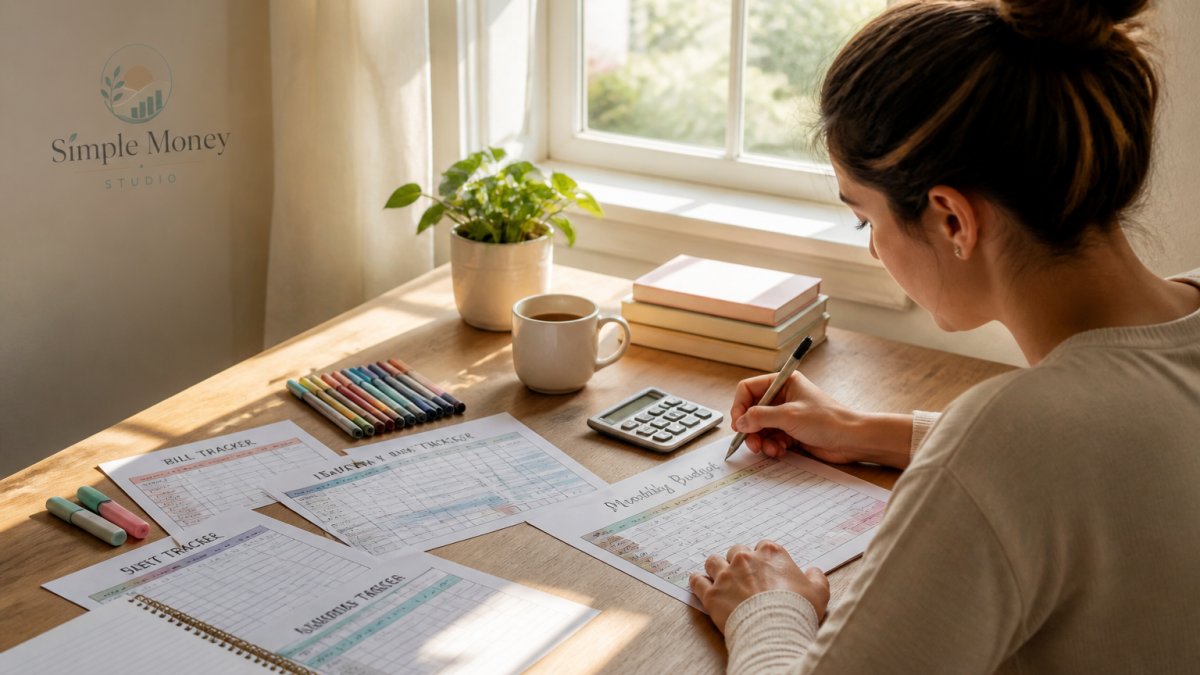
This matters because budgeting tools for visual learners work differently than apps that hide everything behind dashboards and notifications. You're not checking a phone, you're looking at something tangible. That shift changes how you engage with your money. People who use visual budgeting systems stick with them longer because the act of writing things down and seeing progress creates a feedback loop that apps struggle to replicate.
The printable budget tracker approach also removes decision fatigue. You're not scrolling through menus or deciding which notification to dismiss. You open your tracker, update a few numbers, and see where you stand. That simplicity is the whole point.
1-Hour Budget Setup Guide: Build Your Foundation Fast
The 1-Hour Budget Setup Guide walks you through creating a simple monthly budget using four clear buckets: income, bills and fixed expenses, weekly spending, and savings and debt goals. You don't need hours of setup or complex spreadsheets. The framework is intentionally simple so you can actually finish it.

Here's what the process looks like. You gather your last 30-60 days of transactions and your bill list. Then you work through the guide step by step: calculate monthly income, list bills with due dates, estimate essential spending from your recent history, and assign what's left to weekly spending, savings, and debt. That's it. Most people finish in under an hour.
The real value is that this budget actually reflects how you live. It's not some theoretical ideal budget. It accounts for your actual groceries, your actual gas costs, your actual subscriptions.
| Step | Time | What You'll Do |
|---|---|---|
| Gather information | 10 min | Collect bank statements, bills, paycheck stubs |
| Calculate income | 15 min | Convert weekly/biweekly pay to monthly total |
| List bills | 15 min | Write down each bill, amount, and due date |
| Estimate spending | 10 min | Review recent transactions for essential categories |
| Assign remaining money | 10 min | Decide weekly spending, savings, and debt amounts |
The guide is built for people who've never budgeted before or who feel overwhelmed by complicated systems. It doesn't require financial knowledge. It just requires honesty about what you actually spend.
Money & Bills Organizer: See Your Monthly Picture at a Glance
A monthly money organizer does one job: keep everything about your bills in one place so you stop worrying about what's due when. Instead of checking different apps or trying to remember which bills you've paid, you have one document that shows your income, bills, what's been paid, and what still needs attention.
The Money & Bills Organizer includes a monthly overview page where you can see total income, total bills due, total paid so far, and total still due at a glance. There's a bill calendar so you can mark paydays and due dates. There's a payment log to track what you've already sent out. And there's a subscription list so annual or quarterly charges stop being surprises.

What makes this different from just keeping a list in your phone is the weekly check-in routine. You spend five minutes once a week looking at what's due in the next seven days. That's it. Five minutes. But that small habit means you never miss a payment and you always know where you stand.
The tool also includes space for notes and action items. If you realize you need to call your internet provider to negotiate a lower rate, you write it down. If you spot a bill you want to cancel next month, you note it. That way you're not trying to remember everything in your head.
Debt & Savings Tracker: Make Progress Visible With Charts and Graphs
This is where budgeting tools for visual learners really shine. A debt and savings tracker turns abstract numbers into something you can see improving. Instead of "I paid $500 toward my credit card this month," you see a progress bar getting filled in. Instead of "I saved $200," you see your emergency fund bar growing.
The Debt & Savings Tracker helps you choose a payoff strategy first. You decide between the debt snowball (focus extra money on the smallest balance for quick wins) or the debt avalanche (focus on the highest interest rate to save more over time). That choice matters because it changes what you're optimizing for: motivation or total interest saved. The tracker explains both so you can pick what fits your situation.

Once you've chosen your strategy, you list each debt with its starting balance, current balance, minimum payment, and interest rate. You update it once a month. Then you shade in progress bars as balances drop or savings grow.
The tracker also includes monthly and quarterly check-in pages. Monthly, you note your biggest win and biggest challenge. Quarterly, you step back and see how much has actually changed. That perspective shift is powerful when you're grinding through debt payoff.
Printable Budget Tracker vs. Budgeting Apps: Which Fits Your Style
The choice between a paper budget tracker and a budgeting app comes down to one thing: how you actually engage with your money. Apps are convenient. They sync across devices. They send notifications. But convenience isn't the same as effectiveness.
A printable budget tracker requires you to sit down and write things down. That friction is a feature, not a bug. The act of writing creates a memory connection that scrolling through an app doesn't. You're also less likely to ignore a printed tracker sitting on your desk than a notification you can dismiss with one tap.
Apps work if you're the kind of person who checks them regularly. But many people download a budgeting app, use it for two weeks, and then forget it exists. With a printable tracker, forgetting is harder because it's physically there.
| Aspect | Printable Tracker | Budgeting App |
|---|---|---|
| Setup time | 1 hour | 15-30 minutes |
| Update frequency | Monthly or weekly | Daily or weekly |
| Learning curve | Minimal | Depends on app |
| Cost | One-time purchase | Free or subscription |
| Engagement level | High (writing required) | Lower (scrolling) |
| Best for | Visual learners, accountability | Convenience seekers |
The printable approach also works better if your income varies. Side gigs, freelance work, seasonal jobs, those don't fit neatly into app categories. With a tracker, you just write down what you actually made that month and adjust your budget accordingly.
Savings Goal Tracker Printable: Watch Your Goals Come to Life
A savings goal tracker printable turns "I want to save money" into "I'm saving for this specific thing by this specific date." That shift matters. Vague goals don't motivate. Specific targets do.
The tracker lets you list each goal: emergency fund, car repair, vacation, down payment. For each one, you write the target amount, your starting amount, and how much you'll contribute monthly. Then every month you update your current balance and shade in a progress bar.
Watching those bars fill in is what keeps you saving when you could be spending. It's the visual version of momentum. You see the emergency fund bar at 40 percent full and you think, "I'm close. I can keep going." That psychological boost is real.
The tracker also includes space to write why each goal matters to you. That matters. "Emergency fund" is abstract. "Emergency fund so I don't panic if my car breaks down" is concrete. Connecting your goals to real outcomes keeps you focused.
Get Started With the Complete Starter Pack
If you're starting from scratch, buying individual trackers works. But the Starter Pack bundles all four tools together at a better value. You get the 1-Hour Budget Setup Guide, Money & Bills Organizer, Debt & Savings Tracker, and Subscription Cleanup Planner all designed to work together as one system.
The Starter Pack costs $47.96, a $20 savings compared to buying each tool individually. More importantly, the tools speak the same language. Your budget uses the same four-bucket framework as your organizer. Your savings tracker connects directly to the money you freed up in your budget. Everything fits together.
Here's how it works: Set up your budget using the guide. Run your month using the organizer. Track your progress using the debt and savings tracker. Then use the subscription planner to find extra money you didn't know you had. That money goes straight to your savings and debt goals. It's a complete system, not random tools.
Conclusion
Frequently Asked Questions
What makes budgeting tools for visual learners different from regular budgeting apps?
Visual budgeting tools use charts, progress bars, and color-coded sections to show your money situation at a glance, rather than requiring you to read numbers in lists or navigate app menus. Printable trackers let you see your entire budget on one page, making patterns and progress instantly clear. For visual learners, this approach is more intuitive and memorable than scrolling through digital screens.
Can a printable budget tracker actually help me stick to a budget better than an app?
Yes, for many people. The physical act of writing and seeing your budget in print creates stronger memory recall and accountability. The 1-Hour Budget Setup Guide helps you build a simple budget you can actually use, and the Money & Bills Organizer gives you a tangible weekly check-in routine that keeps you engaged without requiring daily app notifications.
How do budget charts and graphs help me manage my money better?
Charts and graphs turn abstract numbers into visual patterns you can see instantly. The Debt & Savings Tracker includes progress bars and monthly check-in sheets where you shade in boxes to track debt payoff and savings growth. Seeing a progress bar fill up or a debt balance drop creates real motivation, even when numbers move slowly. Visual representation makes your financial wins feel more real and keeps you encouraged to continue.
What should I look for in a savings goal tracker printable?
A good savings goal tracker printable should show your target amount, starting balance, current progress, and monthly contribution in one clear view. The Debt & Savings Tracker includes space to write why each goal matters and prompts for your first action, so goals feel personal and doable. Look for progress bars you can shade in or color, a monthly check-in section to celebrate wins, and a quarterly summary to see bigger-picture improvements over time.
Budgeting tools for visual learners work because they turn abstract numbers into something you can see and touch. Whether you choose individual trackers or the complete Starter Pack, the key is picking a system you'll actually use. Simple Money Studio's printable tools are designed specifically for people who feel overwhelmed by apps and need a tangible way to take control of their finances. Get started with the Starter Pack and build a money routine that actually sticks.